The downgrade is the news
- FY27 revenue guidance
- 1% to 2% in constant currencyInfosys had forecast growth of 1.5% to 3% in July.
- Q2 revenue
- ₹49,244 croreConstant-currency revenue grew 1.5% year on year and 1.2% sequentially.
- Operating margin
- 21%The full-year margin guidance remains 20% to 22%.
Infosys on Friday cut its FY27 constant-currency revenue growth forecast to 1% to 2%, from the 1.5% to 3% range it issued in July. September-quarter revenue was ₹49,244 crore, while constant-currency growth slowed to 1.5% year on year and 1.2% sequentially. Operating profit was ₹10,330 crore and the margin was 21%. Its American depositary receipts fell 8% in pre-market trade after the results.
The change is more serious than an ordinary narrowing of guidance. Infosys lowered both ends of its range, abandoning even the previous minimum. Most analysts had expected only the upper end to fall to 2.5%, Reuters reported. The revised midpoint is 1.5%, below the 1.9% constant-currency growth achieved in the first half. The forecast therefore offers no evidence of a second-half recovery. It says that subdued client spending, weaker volumes and pricing pressure are lasting longer than Infosys expected three months ago.
The guidance cut matters more than the reported profit growth because it lowers the revenue base from which future earnings must grow.
AI is growing inside Infosys without yet lifting Infosys as a whole.
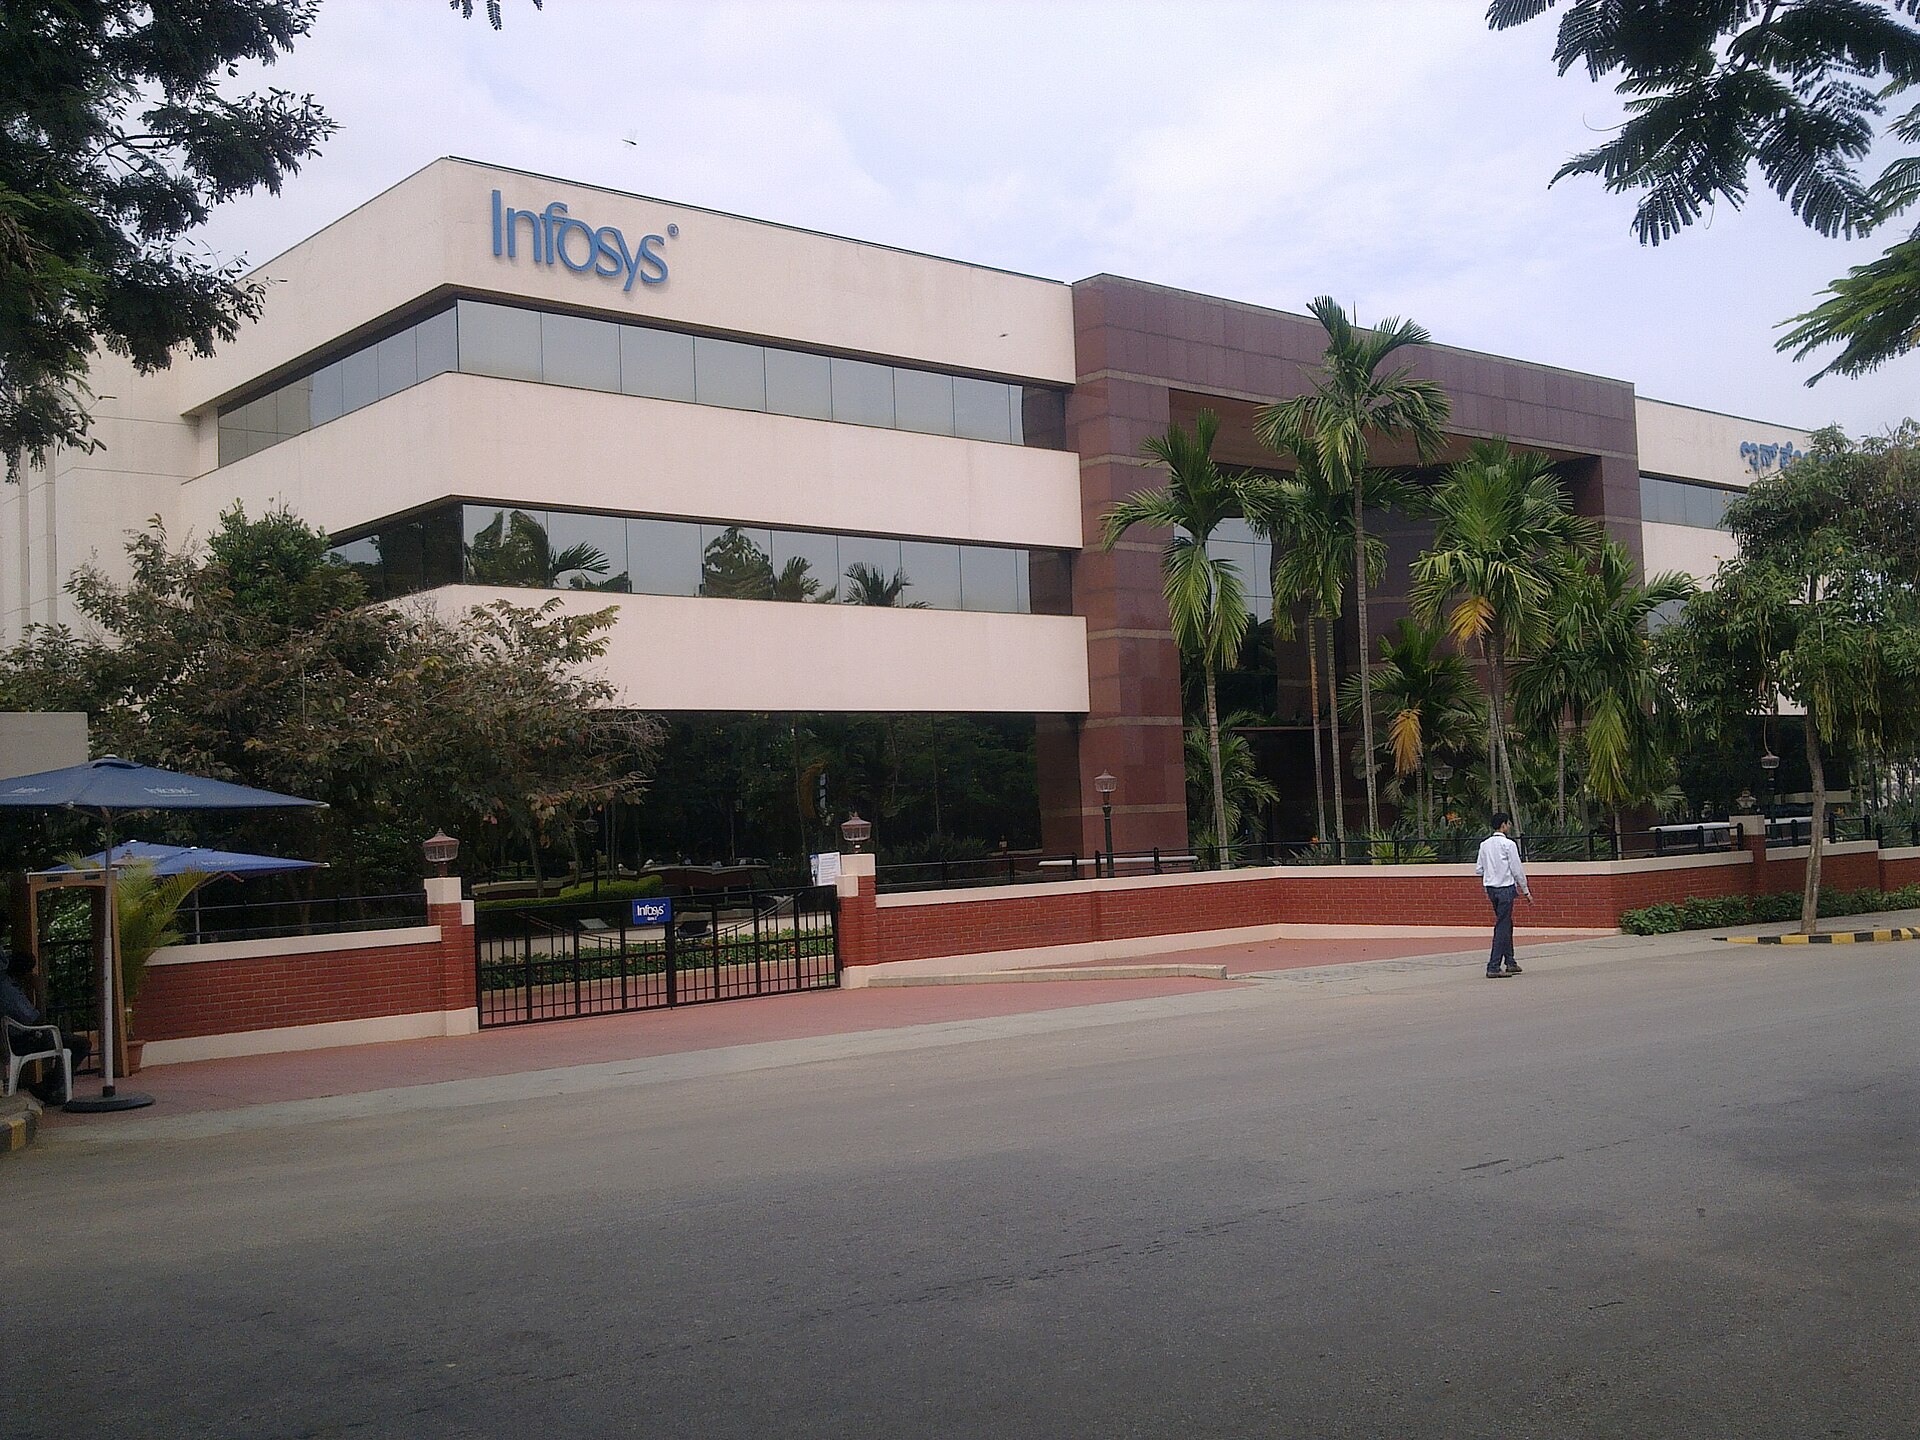
AI growth has a cost
- AI revenue share
- 10.5%The share increased from 8.2% in the June quarter.
- AI revenue growth
- 29% sequentiallyInfosys reported the change from the preceding quarter.
- North American revenue
- Down 1.5%North America contributes more than half of Infosys revenue, according to Reuters.
Infosys presented artificial intelligence as the quarter’s strongest business. AI revenue grew 29% sequentially and reached 10.5% of total revenue, up from 8.2% in the June quarter. Yet company-wide constant-currency growth slowed from 2.4% year on year in the June quarter to 1.5% in September. North American revenue, which contributes more than half of sales, fell 1.5%, its weakest performance in two years, Reuters reported.
AI is growing inside Infosys without yet lifting Infosys as a whole. Chief financial officer Jayesh Sanghrajka said competitive intensity, subdued volumes and clients’ demands to receive AI-led productivity benefits were reflected in the lower forecast. The financial mechanism is direct. Infosys earns revenue from AI projects, but automation can reduce the people and hours required for existing work. Clients can then demand lower prices or outcome-based contracts. Retail and high-technology customers also cut discretionary projects. AI revenue growth does not show how much traditional revenue it replaces or compresses.
The figures show that fast AI revenue growth can coexist with weaker company-wide growth because clients also demand that productivity gains reduce prices and labour requirements.
Margins provide the defence
- Q2 free cash flow
- $928 millionFree cash flow declined 15.7% from a year earlier but equalled 113.3% of net profit.
- Cash and cash equivalents
- ₹24,350 croreThe balance was reported as at September 30, 2026.
- Interim dividend outflow
- ₹10,531 croreThe board declared a dividend of ₹26 a share after the reporting date.
Infosys retained its 20% to 22% operating-margin forecast and delivered 21% in the quarter. Project Maximus, its cost-efficiency programme, contributed 20 basis points to the sequential margin movement. Currency movements and additional working days provided another 60 basis points. Those gains offset costs from post-sale customer support and acquisitions, according to the company.
Cash generation also remains substantial. Free cash flow was $928 million, equal to 113.3% of net profit, although it fell 15.7% from a year earlier. Infosys held ₹24,350 crore of cash and cash equivalents at September 30. Its ₹26-a-share interim dividend is expected to require ₹10,531 crore. The balance sheet therefore gives Infosys room to preserve dividends and invest through the slowdown. The harder test is operational. Compensation increases, weaker seasonal revenue, large-deal start-up costs and further sharing of AI productivity benefits will weigh on second-half margins. Cost reduction can protect the percentage margin, but it cannot indefinitely replace revenue growth.
Stable margins and ample cash limit the damage, but they do not remove the earnings risk created by weak volumes and lower prices.
The strongest case is the order book
- Q2 large-deal value
- $5.2 billionThe total rose from $3.1 billion a year earlier, according to Reuters.
- Net-new share
- 62%The remainder consisted of renewals or extensions.
- Largest new contract
- More than $2 billionInfosys expects the seven-year contract to add more than 1% to FY28 growth.
The best case against a downbeat reading starts with bookings. Infosys won $5.2 billion of large deals in the quarter, compared with $3.1 billion a year earlier. Some 62% was net new. The total included a new seven-year financial-services contract worth more than $2 billion and a $1 billion renewal. Management expects the larger new contract alone to contribute more than 1% to company growth in FY28.
AI revenue is already material, the operating margin remains at the midpoint of guidance, and free cash flow exceeds net profit. A reasonable positive interpretation is that client spending has not disappeared. It is moving towards fewer suppliers, cost-saving contracts and AI programmes, areas in which Infosys is winning work. That case changes the conclusion from structural decline to a delayed recovery. It does not overturn the FY27 warning. The $2 billion contract begins transitioning only in the latter half of the fourth quarter, and its stated growth contribution belongs to FY28. Total contract value is not current revenue.
Large contract wins make a prolonged decline less likely, although their timing means they cannot repair the lowered FY27 outlook.
Conversion is now the test
- H1 constant-currency growth
- 1.9%The revised full-year guidance is 1% to 2%.
- Q2 large-deal contribution
- $5.2 billion of bookingsAcquisitions contributed 0.4 percentage points to sequential growth.
- FY27 margin range
- 20% to 22%Compensation increases and pricing pressure are expected to weigh on the second half.
The guidance cut leaves two measurable tests. First, North American revenue must stop contracting as retail and high-technology clients decide their next budgets. Second, the large-deal order book must become revenue quickly enough to offset lower prices and AI-led productivity savings. Acquisitions contributed 0.4 percentage points to sequential growth in the September quarter, which makes the underlying volume weakness more important than the headline increase suggests.
Infosys has not disclosed how much AI revenue is entirely new spending and how much replaces conventional outsourcing work. That missing split matters. If AI projects expand while total revenue remains near 1% growth, productivity savings are flowing mainly to customers. If revenue accelerates without pushing the operating margin below the 20% to 22% range, Infosys will have shown that AI can enlarge rather than merely reshape its business. The December-quarter results will provide the next evidence through North American growth, realised pricing, operating margin and the pace at which the $5.2 billion of large deals enters revenue.
The next results must show whether bookings are becoming revenue without forcing Infosys to surrender the margin that made this quarter appear resilient.
Sources
- Press Release - Infosys · infosys.com
- infosys.com: consolifrsinr fy27 q2 and h1 finstatement
- www.infosys.com › investors › reports-filingsAI Revenues at 8.2% in Q1; Resilient Operating ... - Infosys · infosys.com
- This information isn't available right now.
- Infosys cuts forecast as AI spending shift deepens North America slowdown · channelnewsasia.com
- Infosys ADR slumps 8% after company lowers FY27 revenue growth outlook · cnbctv18.com